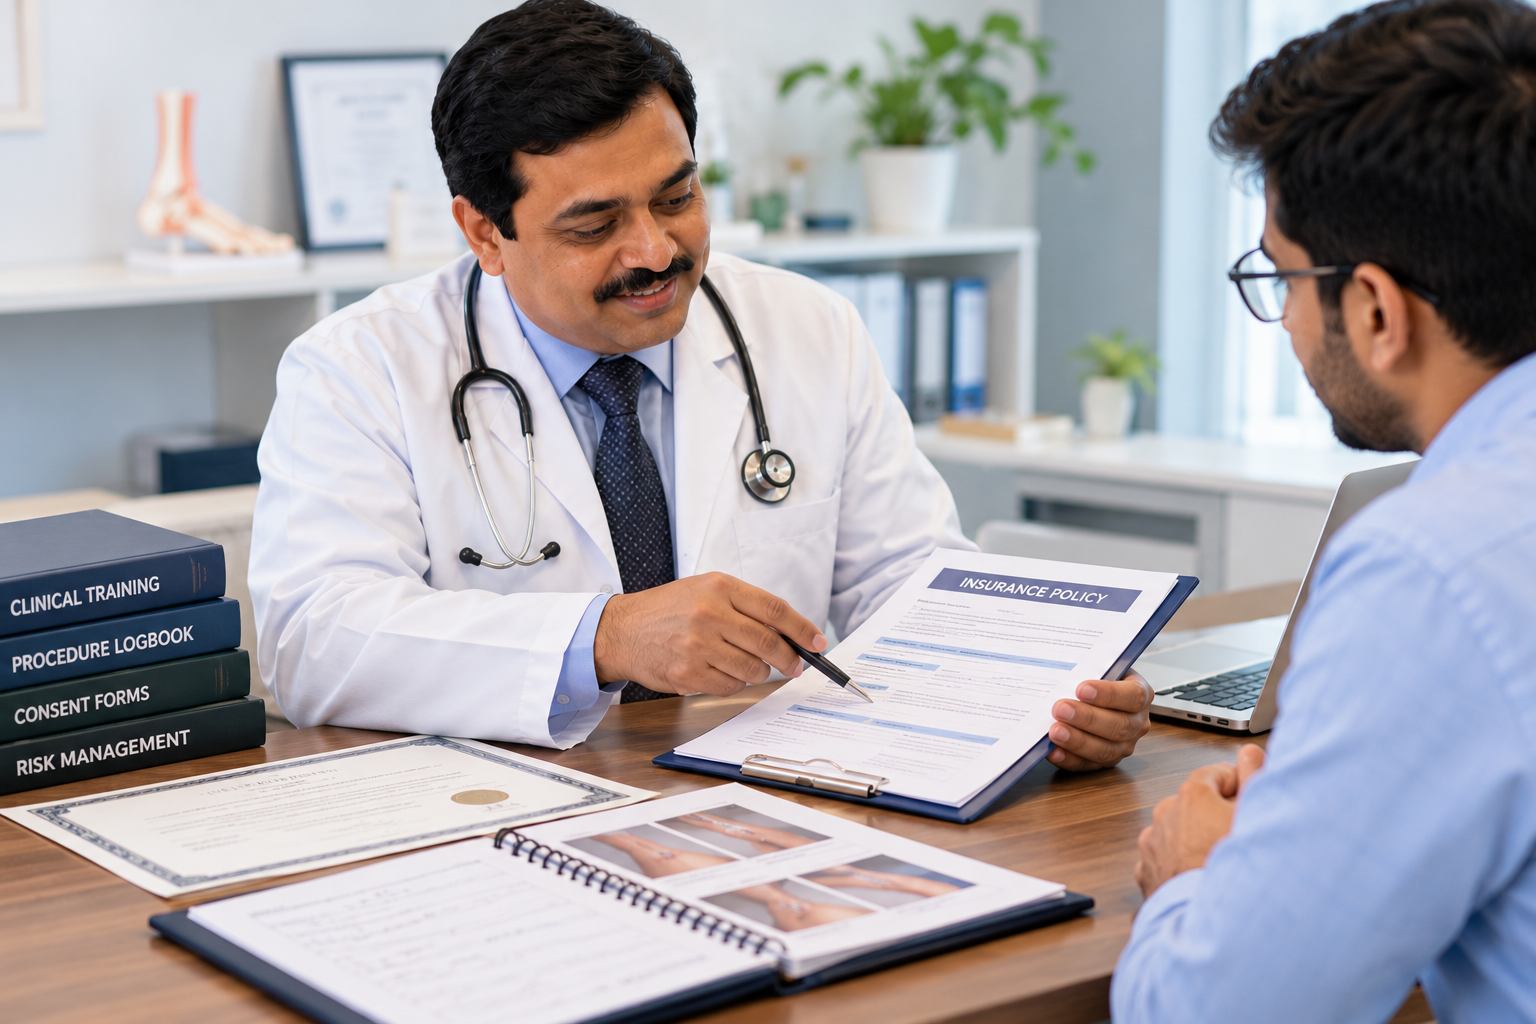
Before adding a new procedure to your practice, reviewing medical indemnity for a new procedure should form part of your pre-procedure checklist. The supplied brief states that many policies may only cover the scope declared at renewal. Before treating the first patient, contact your insurer in writing, provide the requested training and supervised case evidence, clarify exclusions and premium changes, and obtain written confirmation of the updated scope.
Completing a training course does not itself confirm that an existing indemnity policy covers the newly learned procedure. Doctors should verify coverage directly with their insurer rather than assuming that general professional indemnity automatically extends to every new service.
Professional indemnity policies operate according to their individual terms, declared scope, exclusions, and underwriting requirements.
A doctor may purchase or renew cover based on a particular scope of practice. Later, the doctor may complete additional training and introduce a procedure that changes the risk profile of that practice.
For example, a doctor may move from primarily consultation-based care into procedures involving:
Do not assume that the existing policy automatically follows every expansion in clinical activity.
The safer administrative approach is:
New procedure planned → contact insurer → declare new scope → provide requested evidence → clarify exclusions and premium → obtain written confirmation → begin appropriately covered practice.
Doctors developing new clinical services can also review Practice management for doctors.
A training certificate proves that you completed the specified training. It does not by itself establish insurance coverage.
Before introducing the procedure, send the insurer a clear description of what you intend to offer.
Ask specifically:
Keep the insurer’s written response with your practice records.
The exact requirements depend on the insurer and policy. The supplied brief identifies training and logbook evidence as important documents to prepare.
An insurer may ask for information such as:
Do not assume that one insurer will request the same evidence as another.
If the insurer asks for additional information, provide it accurately and keep copies of everything submitted.
| Check | What to Send or Verify | Who Confirms It | What to Keep on File |
|---|---|---|---|
| Scope declaration | Written description of the new procedure | Insurer/authorised representative | Declaration and response |
| Training certificate | Relevant certificate or training evidence | Insurer | Certificate and submission record |
| Supervised case log | Requested evidence of supervised experience | Insurer | Logbook and submitted copy |
| Consent template review | Procedure-specific consent documentation if requested | Appropriate insurer/adviser as applicable | Current consent template and correspondence |
| Exclusions confirmed | Ask specifically about procedure-related exclusions | Insurer | Written clarification |
| Premium impact | Request revised premium or additional charge where applicable | Insurer | Quotation/endorsement |
| Written confirmation received | Confirmation that the declared activity falls within the agreed cover | Insurer | Policy endorsement or written confirmation |
Do not rely solely on a telephone conversation for an important scope change. Request written confirmation and retain it.
The supplied brief specifically flags indemnity exclusions for cosmetic procedures as an issue doctors should investigate, but it does not provide a universal list of excluded procedures.
Therefore, avoid assuming that a particular procedure always receives cover or always falls under an exclusion.
Ask your insurer directly about the procedure you intend to perform.
Questions can include:
The policy wording and the insurer’s written confirmation should guide the insurance decision.
The supplied brief does not provide a percentage or fee increase, so doctors should not rely on a generic estimate.
Premium changes may depend on factors considered by the insurer, including the declared procedure and overall scope of practice.
Before investing in equipment or advertising the new service, request:
Include indemnity costs when calculating the financial viability of a new clinical service.
Doctors considering the wider operational costs of adding procedures can review whether a practice management course is worth it.
When reviewing medical indemnity for a new procedure, keep organised evidence of how you acquired the relevant skills.
A useful training file may contain:
A certificate should not substitute for competence. Doctors should ensure that their training and supervised experience appropriately support the procedure they intend to introduce.
Doctors looking for focused practical training can explore Crash courses for doctors.
Run-off cover concerns protection relating to past professional work after active practice or a particular policy arrangement changes or ends.
Its relevance depends on the structure and wording of the indemnity arrangement.
Doctors should ask their insurer:
The supplied brief does not provide a universal run-off period, so obtain policy-specific advice rather than applying an arbitrary number of years.
Patient care comes first.
Address the immediate clinical problem within your competence and arrange escalation or referral where necessary.
At the same time, follow the notification requirements in your indemnity policy.
A practical sequence may include:
Assess patient → provide appropriate immediate care → escalate when required → document objectively → preserve relevant records → review notification requirements → contact insurer according to the policy.
Avoid altering earlier records after an incident. If you add further information later, maintain a clear and appropriately dated record according to your documentation standards.
Do not wait for a formal complaint before checking whether the policy requires notification of an incident or circumstance.
Check your policy’s notification requirements.
Some policies may require notification when an incident, complaint, or circumstance occurs rather than only after a formal legal claim develops.
Because requirements differ, doctors should know the notification pathway before performing the first procedure.
Keep accessible:
This reduces uncertainty when an adverse event occurs.
Insurance represents only one part of risk management.
Before introducing a new procedure, review whether the consent process clearly covers:
The consent documentation should match the actual procedure rather than relying on an unrelated generic form.
Before the first case, establish a standard procedure record.
It can include:
Creating the documentation system before launching the service reduces the risk of inconsistent records.
Doctors adding procedures need to consider training, clinical competence, documentation, facility preparation, and indemnity together.
At Elegance Vidhyalay, doctors can explore structured educational options through Programmes for doctors, including courses intended to develop practical clinical skills.
Dr. Ashutosh Shah, Plastic and Reconstructive Surgeon with 22+ years of clinical experience, contributes clinical experience relevant to procedural training, appropriate case selection, documentation, complication awareness, and understanding the limits of newly acquired skills.
Doctors should still independently verify their insurance arrangements directly with their insurer before adding a new procedure.
Do not assume that it does. Contact your insurer, declare the new procedure, provide requested training evidence, and obtain written confirmation about coverage before beginning the new service.
Requirements vary. An insurer may request a training certificate, course information, supervised case log, or other evidence. Ask your insurer exactly what documentation it requires.
Policy terms vary. Ask the insurer specifically whether aesthetic or cosmetic procedures fall within your cover, carry exclusions, or require a separate scope extension.
The supplied brief gives no fixed timeframe. Ask the insurer about processing time and wait for written confirmation before relying on the extension.
Run-off cover relates to protection for previous professional work after active practice or a particular insurance arrangement changes or ends. Its application depends on the policy.
Follow your policy’s notification terms. If an incident could trigger a notification requirement, contact the insurer according to its specified process rather than waiting for a formal claim.
Reviewing medical indemnity for a new procedure should happen before the first patient receives that procedure, not after a complication occurs.
Notify your insurer in writing, explain the proposed change in scope, provide requested training and supervised-case evidence, ask about exclusions and premium changes, and retain written confirmation of the insurer’s decision.
Most importantly, do not treat a course certificate as proof of insurance coverage. Training, demonstrated competence, appropriate documentation, and adequate indemnity are separate requirements that doctors should address when introducing a new clinical procedure.